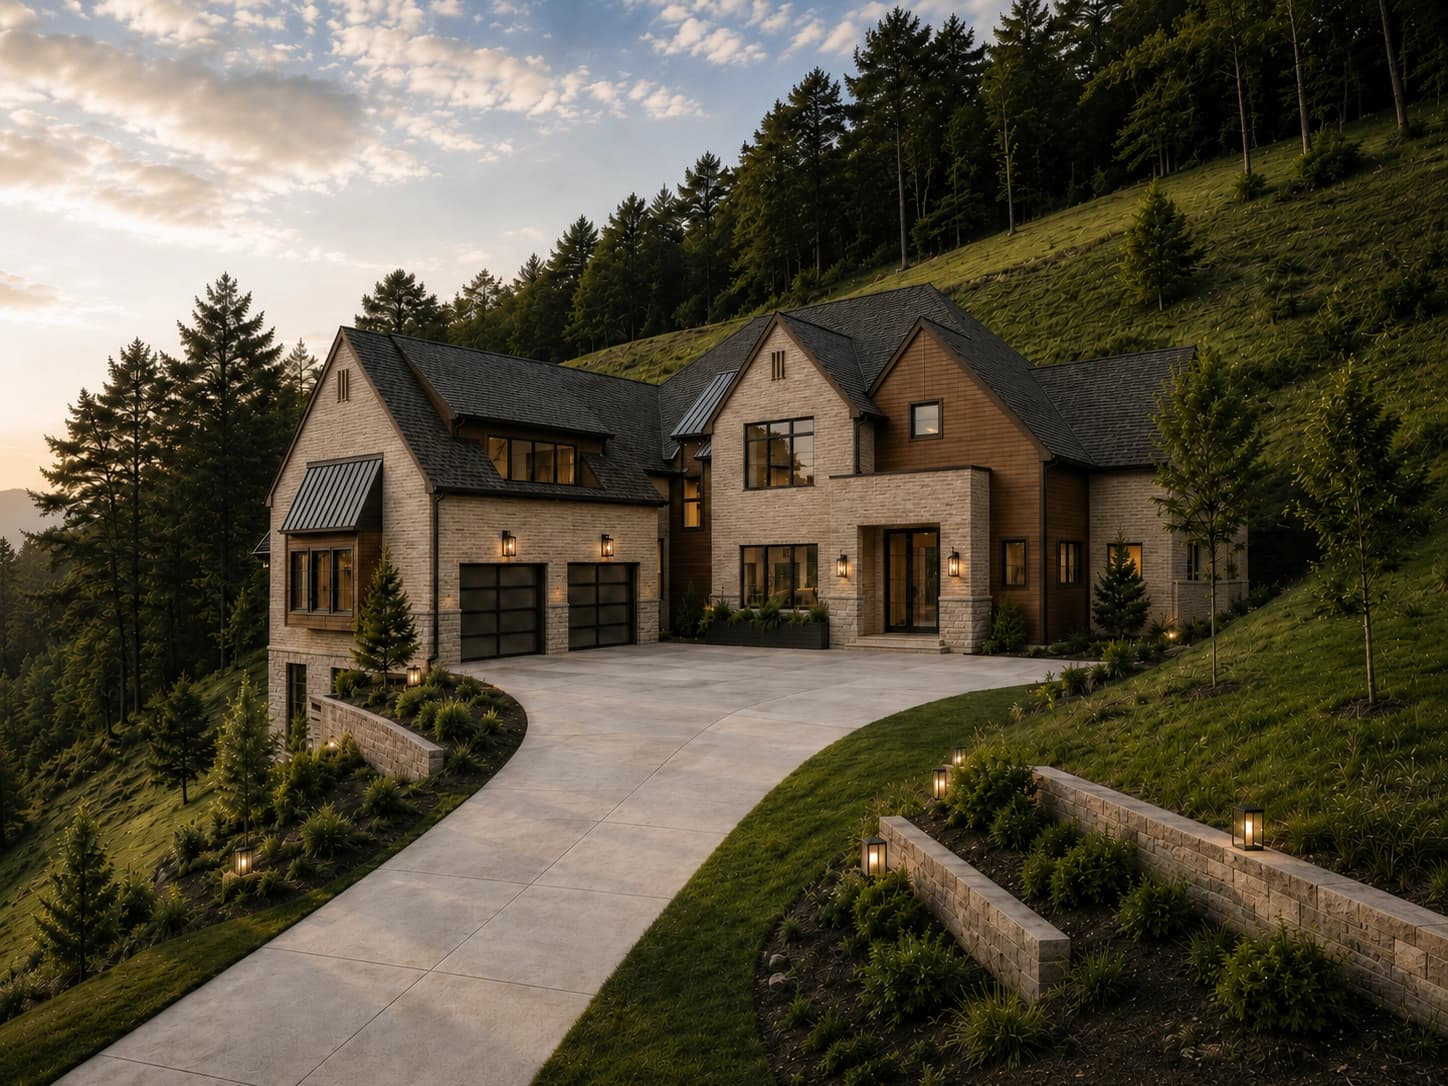
The Monet at Creek Trail, exterior rendering

Harvest River Capital

Our Approach.

How capital is put to work, the projects that qualify, and the controls at every stage.

Our strategy

Asset-backed lending

First-lien construction and renovation loans to builders, developers and investor entities in Middle Tennessee, funded in draws against verified progress.

  • How it is deployed

    Acquisition at closing; construction money in draws, paid only for work in place.

  • How it is overseen

    Payments, draw pace, budget, liens and insurance reviewed every month.

  • How it is repaid

    Repaid from the sale, refinance or lease-up of the completed property, at today's values.

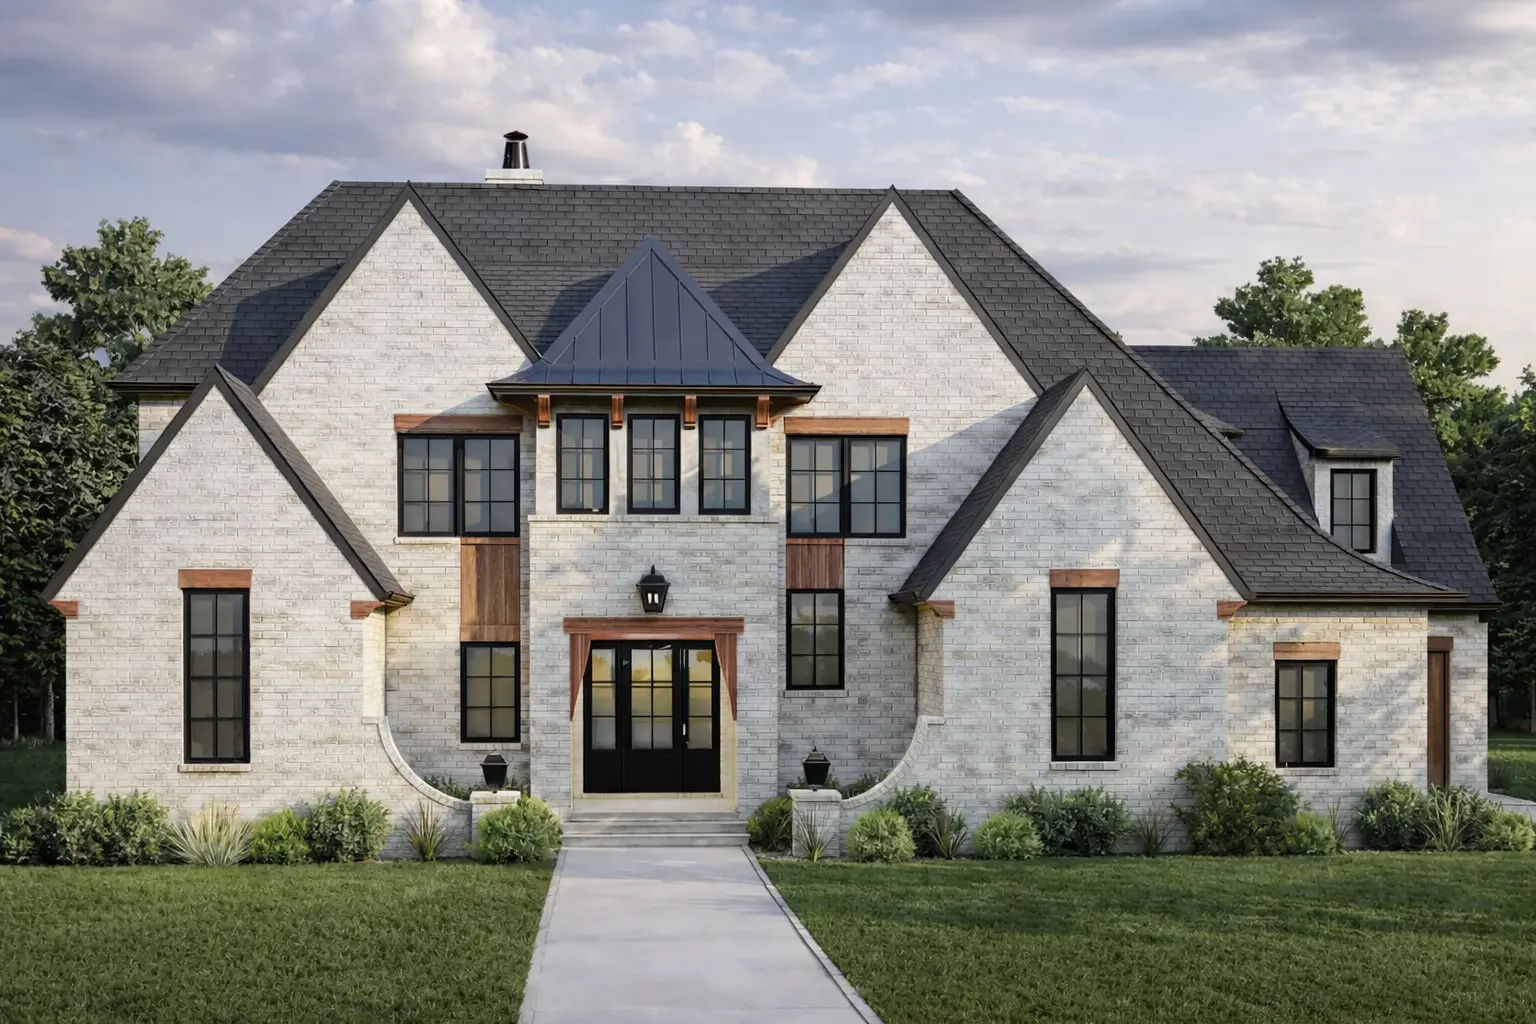
The Monticello at Meadowgreen Dr, exterior rendering 1Rendering
01

Ground-up construction

Single-family, duplex and 2 to 4 unit homes; selected commercial and mixed-use.

02

Renovation

Structural or systems renovation with a clear exit: sale, lease or refinance.

03

Not offered

Second liens, land-only loans, owner-occupied property and consumer loans.

A business borrower applies with the project, budget, amount and exit.

What happens

  • Sponsor package
  • Track record and credit verified

Controls

  • Automatic declines for credit, equity, lien, comparables or licensing

Risk

Risks, and how we manage them

Our controls are designed to reduce risk, not remove it.

A first lien, guaranties and underwriting reduce risk but do not guarantee against loss.

Cost overruns

What could happenCosts can exceed budget and reduce the equity cushion.

How we manage itBudget review against our cost model, required contingency, change-order approval and monthly variance tracking.

Schedule delays

What could happenWeather, permits or trades can push completion and add carrying cost.

How we manage itTrade-sequenced schedules, interest reserves on new construction, and draws suspended when a project falls behind.

Falling values

What could happenHome values can decline before a project is sold or refinanced.

How we manage itValue limits on as-completed appraisals, recent comparable sales, and exits that work at today's values.

Borrower default

What could happenA borrower may stop paying or abandon a project.

How we manage itPersonal and completion guaranties, a defined delinquency timeline, workouts, and the ability to finish a project ourselves.

Liens

What could happenUnpaid trades can file liens against the property.

How we manage itLien waivers with every draw, title date-downs and mechanic's lien title coverage.

Concentration

What could happenLoans grouped in one borrower or county move together.

How we manage itFund-level limits by loan, borrower, county and affiliate loans.

Affiliated transactions

What could happenLoans to projects Harvest River has an interest in create conflicts.

How we manage itThe same underwriting standards and advance approval by the investor Advisory Committee.

Liquidity

What could happenCapital is tied up in loans and projects that take months to repay.

How we manage itRedemption terms are set only by the fund's offering documents.

Oversight

Oversight

01

Development execution

Budget, schedule and quality tracked on every project, with site visits and documented change orders.

02

Loan servicing

Payments, escrows, draws, inspections and payoffs serviced in-house, with a borrower portal.

03

Affiliated transactions

Same underwriting standards, plus advance approval by the investor Advisory Committee.

Team

Leadership

Licensed Tennessee general contractors and active developers.

Eric Brinson

Principal, Harvest River Holdings LLC

Full BC general contractor (TN #79399) and licensed REALTOR (TN #347719). Fifteen-plus years as a developer and builder, leading 250+ real estate acquisitions and development projects across Middle and West Tennessee.

Kenneth McFadden Jr.

Principal, Harvest River Holdings LLC

Full BC general contractor (TN #85098). Ten years in consumer, business and mortgage banking before moving full-time into development, with a focus on highest-and-best-use entitlement.

Governance

Structure

Harvest River Partners

Development and construction: land, entitlements, custom homes and communities.

Harvest River Equity Fund 1, LLC

The fund, and lender of record on fund loans.

Harvest River Holdings LLC

Manager of the fund. Originates and services the fund's loans.

Decisions

How decisions are made

Underwriting authority

Loans are underwritten and approved by the Manager under written lending standards. Final terms are set in the commitment letter and loan documents.

Exceptions

Approved by the Manager only when track record, deal strength and guarantor liquidity justify it, documented in the credit memo and reported to investors.

Affiliated-party oversight

Affiliate loans, and any loan above a concentration limit, need advance approval by the investor Advisory Committee.

Servicing

Harvest River Holdings LLC services the loans and receives borrower-paid fees under the Loan Origination and Servicing Agreement.